
IN A NUTSHELL
-
Despite a world-leading 20.6PC year-on-year increase in passenger traffic as of March 2026, African airlines average a net profit of 1.30 dollars a seat. -
African carriers face the highest unit costs globally, with jet fuel prices 17pc higher than global benchmarks and infrastructure charges 15pc above the average. -
A total of 774 million dollars in airline revenues remains blocked across various African countries, stifling liquidity and investor confidence. -
Intra-continental travel is restricted by visa requirements for nearly 50pc of routes. -
The sector supports 8.1 million jobs and contributes 75 billion dollars to the continent’s GDP.
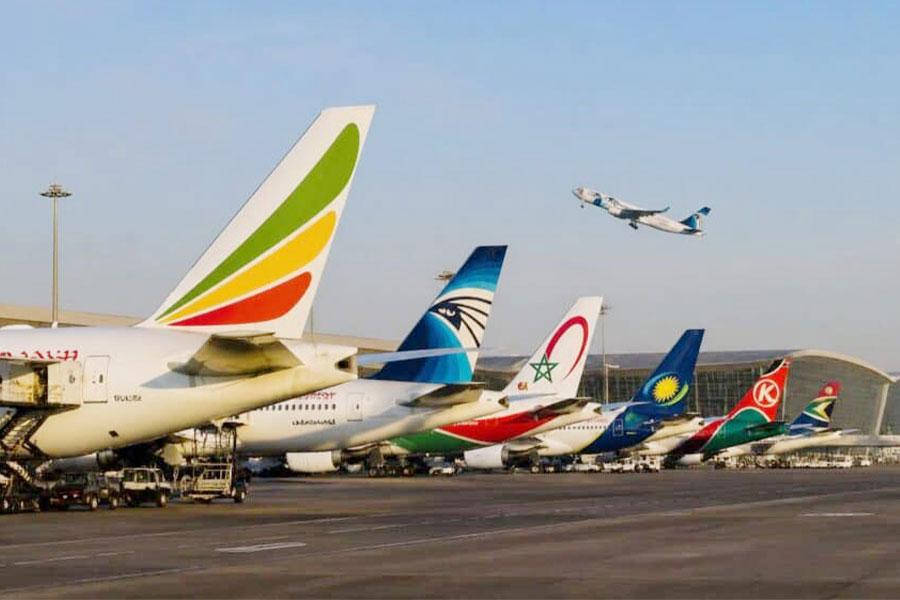
African aviation is entering a contradiction. The continent has the world’s fastest passenger growth, yet its airlines remain among the least profitable, squeezed by high charges, expensive fuel, blocked revenues and political hesitation over integration.
In March 2026, African carriers recorded a 20.6pc year-on-year increase in passenger traffic, the highest growth rate globally. But the average airline on the continent earns only $ 1.3 in net profit a seat flown. The industry is fragmented by regulation, weakened by costs and burdened by governments that often treat aviation less as economic infrastructure than as an easy revenue source.
However, the aviation sector supports 8.1 million jobs across Africa and contributes 75 billion dollars to the continent’s GDP, including 42 billion dollars linked to tourism. Each year, it carries 110 million passengers, equal to 2.9pc of global passenger traffic, and moves 1.2 million tonnes of air freight. Experts following the continent’s aviation business insist that aviation can create prosperity more durably than taxation when governments see it as a strategic enabler.
Ethiopian Airlines Group (EAG) offers both the promise and the pressure that the sector experiences. Already supporting two billion dollars in economic activities and more than half a million jobs across the aviation community, passenger demand is expected to triple over the next two decades. Ethiopian Airlines, the continent’s strongest carrier, performs above the African average, according to Mesfin Tassew, CEO of the Group, although he declined to disclose figures.
“The Ethiopian Airline’s profit margin is higher than the average,” he told Fortune.
He attributed the performance to the Group’s strength and wider network of destinations. But he shifted focus to the wider market. Nearly half of the continent’s 50 airlines are operating at a loss. Japan Airlines performs better because it is more established and has a wider network. The comparison could be unforgiving.
African airlines collectively earn about 200 million dollars a year. Latin America, the next-least-profitable region, earns 10 times as much. Other regions record profits from 6.6 billion dollars to 14 billion dollars. Asia-Pacific airlines earn 3.2 dollars a passenger, nearly three times Africa’s level. In the Middle East, the figure reaches 28.6 dollars, more than 20 times Africa’s profit a seat. Other regions make between 5.70 dollars and 10.90 dollars.
For the past 10 years, African airlines’ global market share has remained at two percent.
